SACCO Loan Management Software: What a Proper Loan Module Should Do
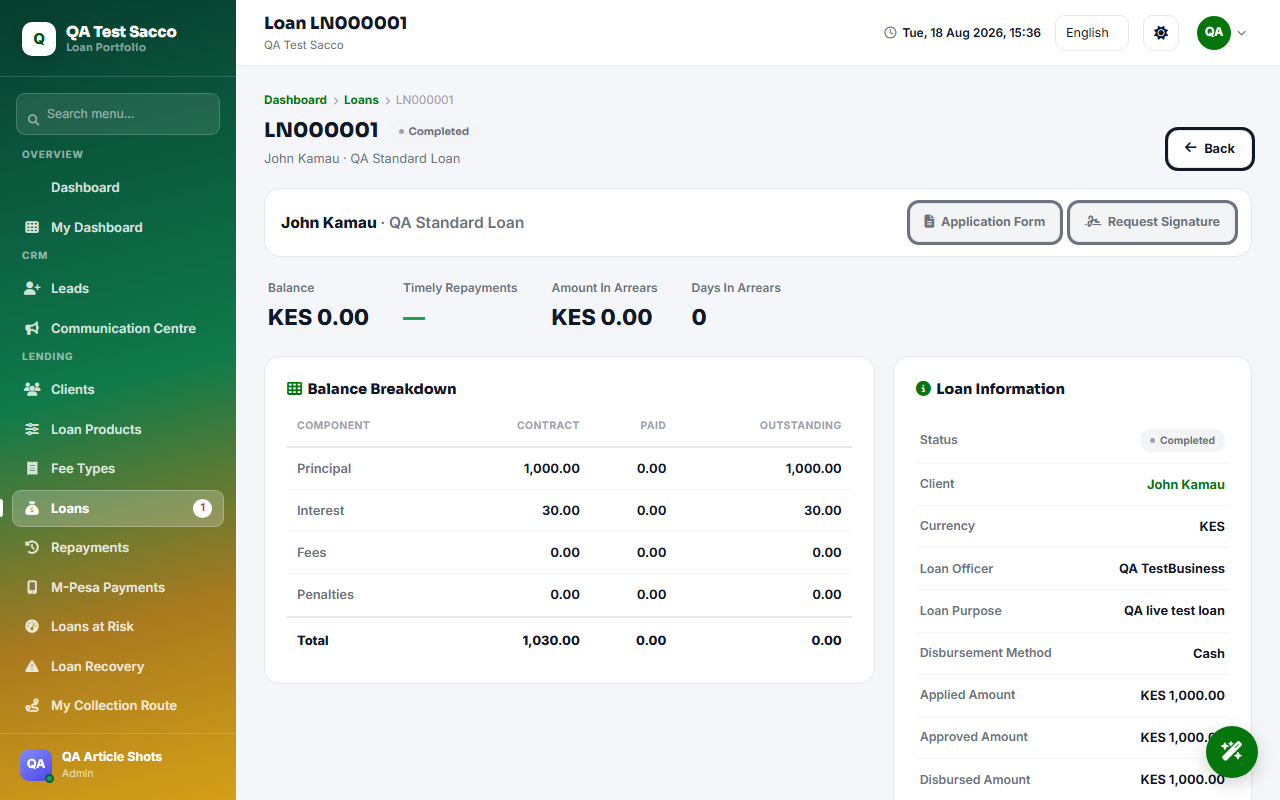
A SACCO's loan book is usually its largest single asset and, at the same time, its biggest operational risk, which is why loan management deserves more than a generic "loans" feature bolted onto member management software. A purpose-built module needs to reflect how SACCO lending actually works, not how a bank or a microfinance institution lends.
That starts with configurable loan products, most SACCOs don't offer one loan, they offer several: an emergency loan with fast approval and a short term, a development loan with a longer term and larger amounts, a school fees loan timed around the academic calendar, each with its own eligibility rules, interest rate, and repayment structure. The software needs to let a SACCO define all of that itself rather than forcing every loan through one fixed template.
Eligibility in a SACCO is usually tied directly to a member's savings and shares, commonly expressed as a loan-to-savings ratio, so the system needs to check that automatically at application time, not leave it to a loan officer's memory. Guarantors add another layer specific to SACCO lending: the module should track each guarantor's committed amount against their own savings and shares, and flag it clearly if a member is already guaranteeing more than their own security can reasonably cover across multiple loans at once, a real risk that's easy to miss when guarantor commitments live in someone's notebook rather than the system.
From there, the same fundamentals apply as any loan software, correct interest calculation (flat or reducing balance), an accurate repayment schedule, real-time arrears flagging, and reports that show the SACCO's actual loan portfolio health, not a snapshot reconstructed at month-end.
pawa Loans's loan module is built specifically around SACCO lending, multiple configurable products, savings-linked eligibility, guarantor exposure tracking, and both interest methods, so the loan book runs the way a SACCO actually lends, not the way generic lending software assumes everyone lends.
Frequently asked questions
What makes SACCO loan software different from generic loan software?
SACCO lending is built around member savings and shares as security, and often multiple configurable loan products with different terms, which generic lending software isn't always built around.
Can one SACCO offer multiple loan products with different rules?
Yes, and it should be able to, most SACCOs offer several loan products (development loans, emergency loans, school fees loans) each with its own eligibility, term, and interest rules.
Does SACCO loan software handle guarantors automatically?
It should track each guarantor's committed amount against their own savings and shares, and flag it if a guarantor is already over-committed on other loans.
Ready to run your SACCO, chama, or microfinance from one dashboard?
Get started