How to Calculate a SACCO Member's Credit Score
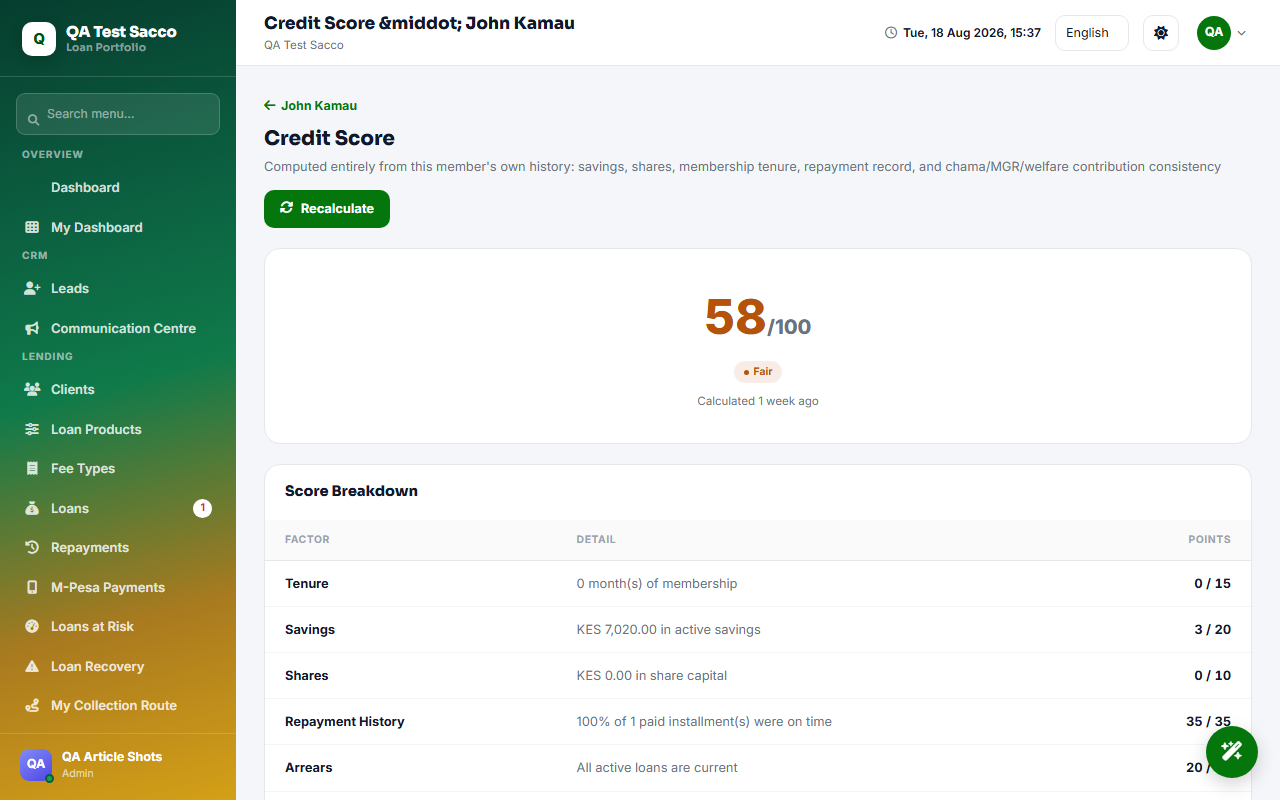
A commercial credit bureau score is built on data most SACCOs don't have direct access to, and it misses data most SACCOs actually do have: a member's real savings discipline, share contribution history, and repayment record inside the co-operative itself. A well-designed internal credit score uses exactly that, and it's often a far more accurate predictor of whether a specific member will repay a specific loan than an external score built on unrelated credit relationships.
A real internal score typically weighs several factors together rather than any single number in isolation: how consistently the member saves relative to their own pattern (a member who saves regularly, even small amounts, is signalling reliability), their share capital relative to what they're requesting to borrow, how long they've been an active member (tenure correlates strongly with lower default risk in co-operative lending), their actual repayment record on any prior loans, including whether payments were on time or chronically late, and participation in group structures like chama or merry-go-round contributions, which is itself a real, observable financial-discipline signal.
None of those factors is meaningful alone. A member with a short tenure but a spotless repayment record on one small loan reads differently than a long-tenured member who's never actually borrowed, and a scoring model needs to weigh recency and volume of evidence, not just tick boxes.
The real value of doing this well is faster, more confident lending decisions, a loan officer reviewing an application backed by an actual computed score across real internal signals can approve responsibly in minutes, instead of relying entirely on personal familiarity with the member or a purely manual judgment call that doesn't scale past a certain SACCO size.
pawa Loans computes a real, seven-factor credit score for every member directly from their own account history, savings consistency, repayment record, tenure, group participation, and more, recalculated automatically as new activity comes in, so lending decisions are backed by the SACCO's own real data rather than guesswork or an external score that doesn't reflect the relationship at all.
Frequently asked questions
What signals matter most in an internal SACCO credit score?
Savings consistency, share capital relative to the amount requested, membership tenure, actual prior repayment record, and participation in group structures like chama or merry-go-round contributions.
Is an internal score better than an external credit bureau score?
For SACCO lending decisions, often yes, a SACCO already has direct access to a member's real savings and repayment behaviour inside the co-operative, which an external bureau score doesn't capture.
Does a high score guarantee loan approval?
No, it's a decision-support signal for the credit officer, not an automatic approval; a single number in isolation is never the full picture.
Ready to run your SACCO, chama, or microfinance from one dashboard?
Get started